Your Local Mortgage Lender
Located in Chula Vista, California
Personalized Mortgage Experience
Angel Hernandez offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Chula Vista, California.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
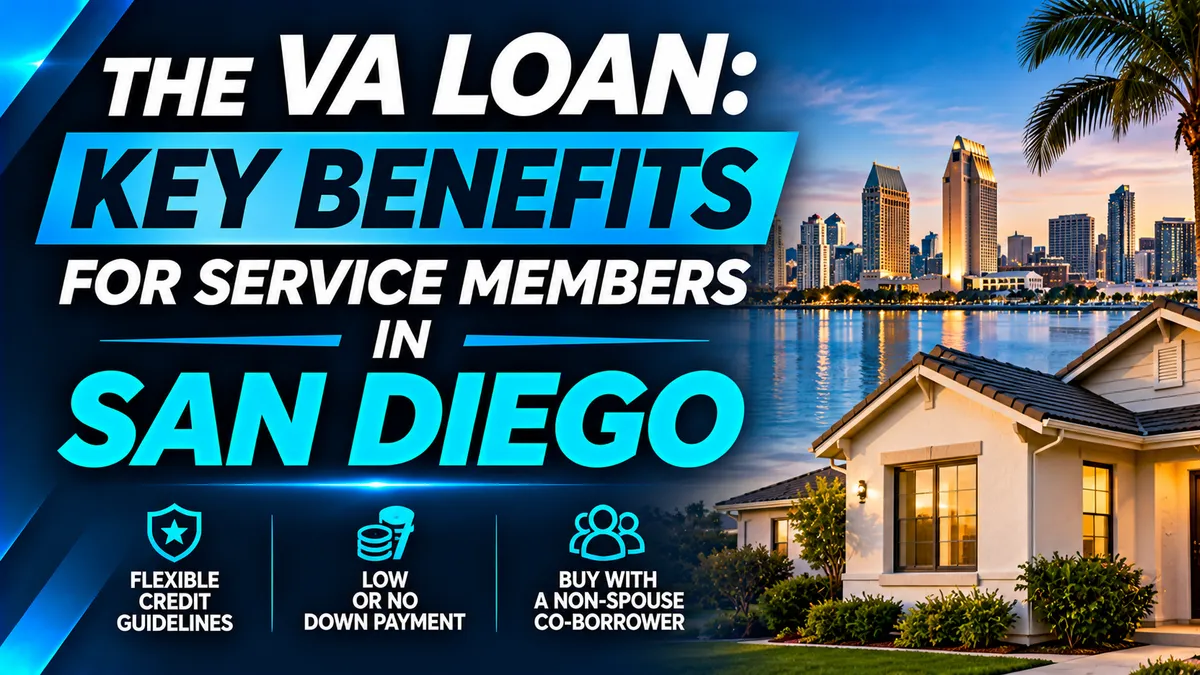
Buying in San Diego With a VA Loan: What Service Members Should Know First With Angel Hernandez
The First Thing to Know About the VA Loan
When a service member tells Angel Hernandez they want to buy a property in San Diego, the first thing he shares is that the VA loan is by far the best loan available. The reason is that it offers multiple exceptions that other types of financing simply do not. Two of the most common misconceptions he hears involve credit scores and who you can buy with.
The VA Does Not Set a Minimum FICO Score
Many buyers believe the VA requires a minimum FICO score. It does not. The VA itself has no minimum credit score requirement. Any minimum you run into is set by the bank or lender, not by the VA. That means a borrower who has been told they do not qualify because of their score may still have options with a different lender.
Can You Use a VA Loan With Someone Other Than Your Spouse?
One of the biggest myths is that a VA loan can only be used with your spouse. Part of that is correct, but it is not the whole story. A VA loan can also be used to purchase a property with someone who is not your spouse. Angel recently helped a client do exactly that.
What Changes When You Buy With a Non-Spouse
The difference is that the borrower does not use their full entitlement. They use half of it. Because of that, a down payment is needed. So while the purchase is possible, buyers should expect to come in with money down instead of the zero down option that comes with full entitlement.
How to Get Started
The first step is simple. Call Angel or visit his website and click “check my budget,” then send in your information so the two of you can begin reviewing the process and help you become a homeowner.
Sources
VA.gov
BenefitS.va.gov
ConsumerFinancialProtectionBureau.gov
HUD.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

